
Door count is one of the first numbers a buyer sees when reviewing a property management company.
It is not the last number they trust.
A portfolio that grew through referrals, reputation, and strong service usually carries less risk than one that expanded through acquisitions or heavy paid marketing. Buyers separate these growth sources because each one says something different about future revenue.
If you are preparing a property management portfolio for sale, your growth story must show more than an upward line. It must show where the doors came from, what they produce, and whether they are likely to remain after a change in ownership.
1. Buyers separate door growth into distinct categories.
A buyer will usually divide your historical growth into at least three groups: reputation-led organic growth, paid-marketing growth, and acquired growth. Reputation-led growth comes from referrals, broker relationships, owner recommendations, and expansion within existing client relationships. Paid-marketing growth comes from channels such as Google Ads, social media, direct mail, lead services, or sponsored industry campaigns.
Acquired growth comes from purchasing another management company or buying a standalone rent roll. Each category has a different cost structure, retention profile, and level of transfer risk. Treating all new doors as one number makes the financial story less credible.
2. Reputation-led organic growth usually receives the strongest underwriting treatment.
Referral and reputation-led growth often demonstrates that your service model produces new business without a proportional increase in acquisition cost. Buyers want to know whether owners recommend your company because of reliable communication, strong maintenance coordination, accurate reporting, and consistent results. Those relationships can be more durable than leads generated only by advertising.
Buyers verify this growth through CRM records, referral sources, signed management agreements, onboarding dates, and owner interviews. They may also review online reputation, broker relationships, and the percentage of new doors that came from existing clients. A steady pattern across several years is more valuable than one unusually strong quarter.

3. Buyers verify organic growth through a historical door bridge.
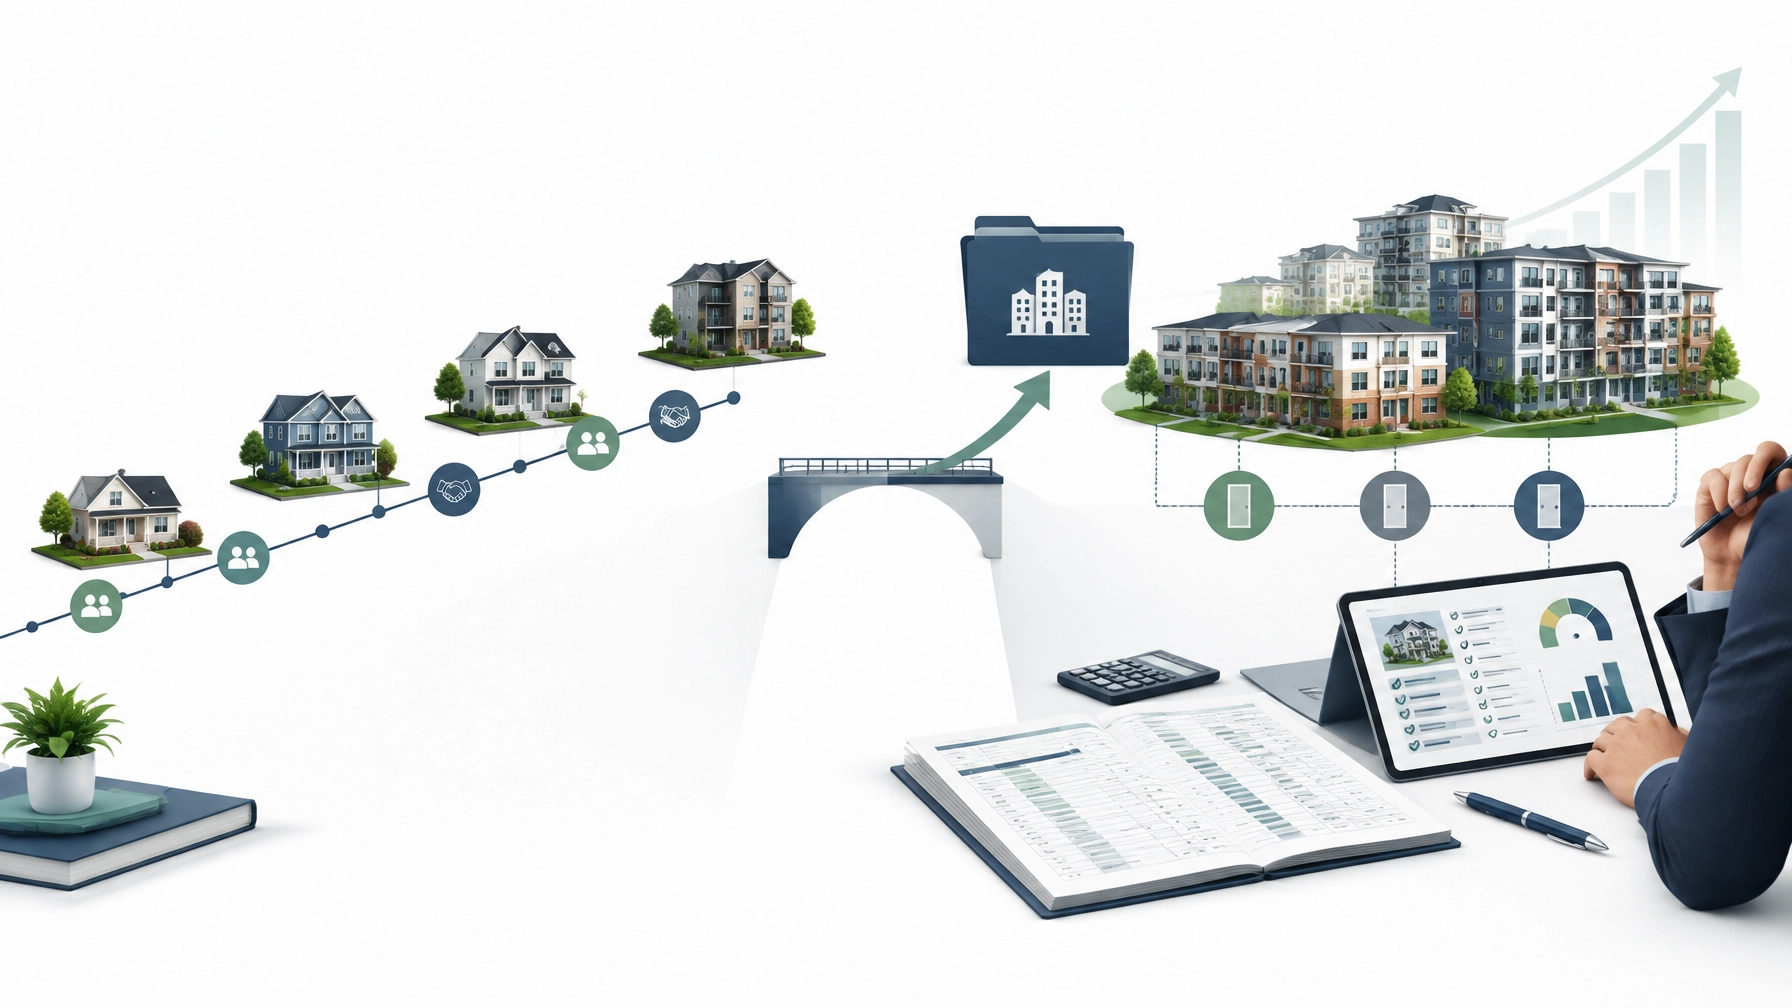
A door bridge tracks how the portfolio changed over time. It begins with the opening door count for a period, then adds new organic doors, acquired doors, and same-owner expansion before subtracting lost doors.
A useful bridge may look like this:
| Growth category | What the buyer wants to see |
|---|---|
| Beginning doors | Reconciles to prior-year records and management reports |
| Referral and reputation-led doors | Source of referral, signed date, and retention history |
| Paid-marketing doors | Channel, spend, lead volume, conversion, and payback |
| Acquired doors | Purchase date, transaction terms, starting count, and churn |
| Same-owner expansion | Additional properties added by existing clients |
| Lost doors | Reason for termination, date, and revenue impact |
| Ending doors | Reconciles to current portfolio records |
The bridge should reconcile to your property management software, general ledger, management agreements, and monthly reporting. If the numbers do not match across those sources, a buyer may question the entire growth history.
4. Acquired growth carries a different type of risk.
An acquisition can add hundreds of doors immediately. It can also add contracts, staff, systems, owner relationships, fee structures, and unresolved operational problems that were not visible before closing.
A buyer will examine what happened after each prior acquisition. They will review first-year churn, management agreement transfers, fee changes, owner complaints, staff departures, and integration costs. If a company added 500 doors through acquisition but retained only 380 after twelve months, the headline growth number is misleading.
Buyers may also discount acquired revenue until the portfolio has demonstrated stable retention under the current operating model. In some transactions, the buyer may use a holdback or earnout tied to door retention, recurring revenue, or client continuity.
5. The quality of an acquisition depends on post-close retention.
The purchase date is not the end of acquisition analysis. It is the beginning of the retention test.
For every acquired portfolio, you should be able to show the starting door count, the number transferred successfully, the number lost during the first 30, 90, and 180 days, and the current count. Buyers will also want to know whether lost doors left because of pricing, service problems, contract issues, seller relationships, or normal property sales.
A clean integration record can reduce the risk discount. It shows that your company can absorb another portfolio without creating service failures or losing the expected revenue.

6. Paid marketing is internal growth, but buyers underwrite it separately.
Paid marketing is not the same as buying a management company. It is still internally generated growth. However, buyers will not treat a door acquired through a large advertising budget the same way they treat a door obtained through a trusted owner referral.
They will examine customer acquisition cost, lead-to-client conversion, average revenue per door, gross margin, early churn, and payback period. They also want to know whether growth would continue if marketing spend were reduced after closing.
A company that spends $100,000 to add doors may show strong revenue growth while producing little incremental profit. If the financial statements do not connect marketing expense to new management revenue, the growth rate can appear stronger than the underlying economics.
7. Marketing spend can distort the growth story in the financials.
A buyer reviews both the revenue line and the expense required to produce that revenue. If marketing costs increased sharply during a growth period, the buyer will test whether the resulting doors created enough recurring profit to justify the spend.
The financial story should separate:
- Brand and reputation expenses.
- Lead generation and advertising expenses.
- Sales payroll and commissions.
- One-time campaign costs.
- Ongoing marketing required to maintain the current growth rate.
- Revenue and gross margin from the doors generated by each channel.
You should not present marketing as a one-time expense if the buyer must continue spending at the same level to replace normal churn. Conversely, you should not treat a temporary launch campaign as a permanent operating cost if the channel has produced a durable client base with low ongoing expense.
The buyer is looking for normalized earnings. They want to understand what the business can earn after a reasonable owner takes over and continues the necessary growth activity.
8. Same-owner expansion can be a strong form of organic growth.
A property owner who adds more properties to your management portfolio is often a valuable signal. It suggests trust, service satisfaction, and an opportunity to grow without finding a completely new client.
Buyers will verify whether the expansion came from the same ownership group, how long the original relationship has existed, and whether the added properties carry similar margins. They may also review whether the expansion resulted from a structured account-management process or from the seller’s personal relationship.
Same-owner growth is still subject to concentration risk. If one owner added 200 doors but represents a large portion of total revenue, the account may support growth while also creating a significant exposure.
9. Buyers compare growth with retention and margin by cohort.
A large number of new doors is not enough. Buyers want to know whether the doors stayed, what revenue they generated, and how much it cost to service them.
Cohort analysis groups doors by the period and source in which they entered the portfolio. For example, you might compare 2023 referral doors, 2023 paid-marketing doors, and 2023 acquired doors across retention, revenue per door, service costs, and margin.
This analysis can reveal that one channel produces fewer doors but better clients. It can also show that a high-growth channel produces low-value accounts, heavy maintenance demands, or flattened growth after the initial campaign.

10. The financial statements should tell the same story as the door bridge.
Your income statement should support the operational explanation. If door count increased by 20%, the buyer will expect to see a logical relationship between that increase, management fee revenue, payroll, software costs, marketing expense, and EBITDA.
The buyer may ask:
- Did recurring management revenue grow with the door count?
- Did revenue per door remain stable?
- Did payroll increase faster than the portfolio?
- Did acquired doors carry lower margins?
- Did marketing spend rise before or after the growth?
- Did churn increase during periods of rapid expansion?
- Were integration costs recorded clearly?
A clean financial package connects doors to revenue and revenue to cash flow. It also separates recurring management fees from leasing income, maintenance revenue, project income, and other non-recurring items.
This is central to understanding how property management businesses are valued. Buyers are purchasing expected future earnings, not a historical door count by itself.
11. Deal structure may reflect the buyer’s confidence in your growth.
When organic growth is well documented and retention is strong, the buyer may be more comfortable paying for the business through a conventional closing structure. When recent growth depends heavily on acquisitions or paid marketing, the buyer may seek additional protection.
That protection can include a seller note, an earnout, a holdback, or a purchase price adjustment tied to retained doors and recurring revenue. These terms do not automatically mean the buyer rejects the growth. They indicate that the buyer wants the final price to reflect what remains after transition.
Your historical acquisition results matter here. A consistent record of successful integrations can reduce the need for aggressive protections. A pattern of post-close churn will likely produce more conservative underwriting.
12. Present growth as a repeatable operating system.
A buyer does not need every new door to come from referrals. Paid marketing and acquisitions can both create value when the economics are clear and the risks are controlled.
The strongest presentation shows a repeatable system. It explains how leads become signed management agreements, how new doors are onboarded, how service capacity expands, and how client retention is measured. It also shows which parts of that system depend on the owner.
If your company is listed as a property management portfolio for sale, the buyer will review the portfolio as an operating business rather than a static collection of contracts. Clear systems make the growth more transferable.
Your growth story should answer four questions:
- Where did the doors come from?
- How much did each source cost?
- How many doors and owners stayed?
- What earnings did those doors produce?
That is the difference between reporting growth and proving growth.
Organic growth, paid-marketing growth, and acquired growth can all contribute to a strong property management company. Buyers simply assign different levels of confidence to each source.
The best preparation is a clean door bridge, reliable cohort data, reconciled financial statements, and a clear record of post-acquisition retention. If you are exploring property management M&A, a valuation review with Vision Fox Business Advisors can help you understand how buyers may underwrite your growth before you enter a formal sale process.
The process can remain private and exploratory. You do not need to list your company to gain a clearer view of how your growth history affects value.

